 Pomegra
Geopolitics
MAJOR
5d ago5 min read
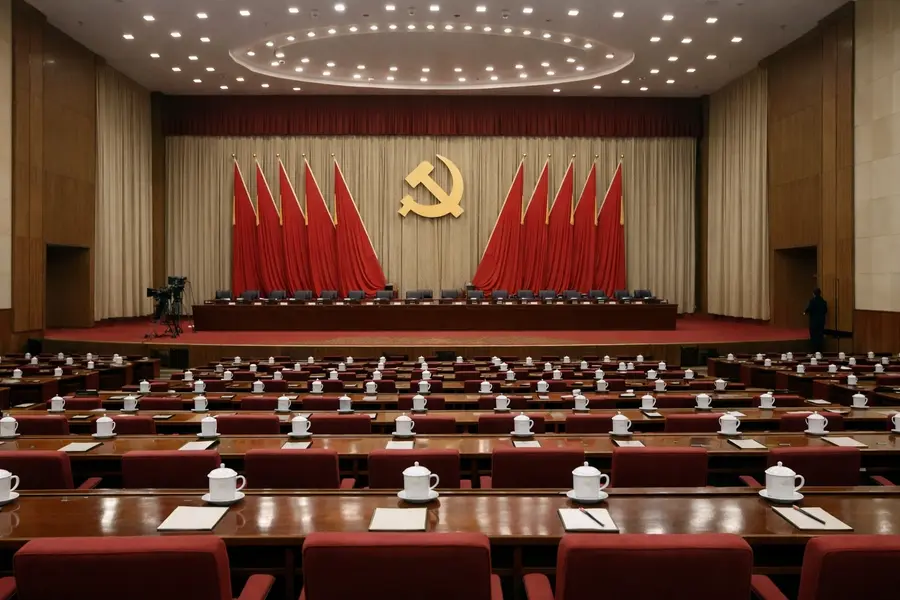
China's Fifth Plenum 2026: Xi Presses Party Discipline
China's four-day Communist Party plenum opened with Xi Jinping pushing stricter discipline and an anti-corruption drive ahead of an expected fourth term.
Daily Digest
Daily Digest
Pomegra Newswire - Page 4 of 108
Daily market coverage from the PomiNews desk - every story with sentiment, impact, and key takeaways
China's four-day Communist Party plenum opened with Xi Jinping pushing stricter discipline and an anti-corruption drive ahead of an expected fourth term.
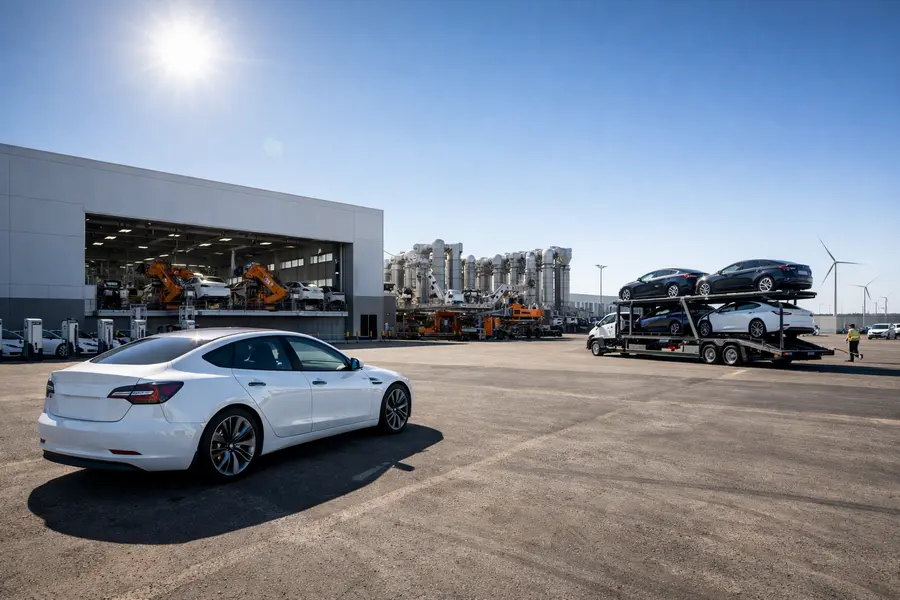
Tesla shares rose about 5% to near $392 on Monday after Barclays upgraded TSLA to Overweight with a $450 target and Latvia became the 10th EU state to approve FSD.
The ECB is expected to hold its policy rate at 2.50% on Oct. 29 as five central banks meet, while the Bank of Japan signals a possible December hike.
Lumentum rose about 10%, Applied Optoelectronics 9% and Coherent 7% as bullish coverage and AI demand revived optical stocks ahead of November earnings.
Intel shares rose 4% to $90.47 after New Street Research upgraded the stock to Buy, citing an AI-driven server CPU shortage ahead of Q3 results on October 29.
Fair Isaac shares fell 9.2% premarket on Monday after FICO held its mortgage score price at $10, as regulators put VantageScore on equal footing at Fannie Mae and Freddie Mac.
China's STAR50 index has dropped 40% in under four months, erasing about $480 billion as AI stocks reel from demand doubts and US curbs on Chinese equipment.
Verizon beat Q3 2026 profit estimates, raised guidance a third time and signed a $2 billion-plus AWS AI deal, but a revenue miss left shares mixed premarket.
Moderna (MRNA) shares fell another 8% on Monday after leaked melanoma vaccine data showed a 42% cut in recurrence or death risk, extending a selloff in biotech cancer stocks.
Apple briefly passed Nvidia as the world's most valuable company at about $5.1 trillion on iPhone Duo launch day before Nvidia reclaimed the lead by the close.
EQT will buy Range Resources in an all-stock deal that creates a US natural gas producer worth over $50 billion; Range shares jumped about 16% Monday.
Anthropic's public S-1 shows $16.3B in first-half revenue and an $80.7B net loss, and Nvidia, Broadcom and Micron rallied as the ANT listing came into view.
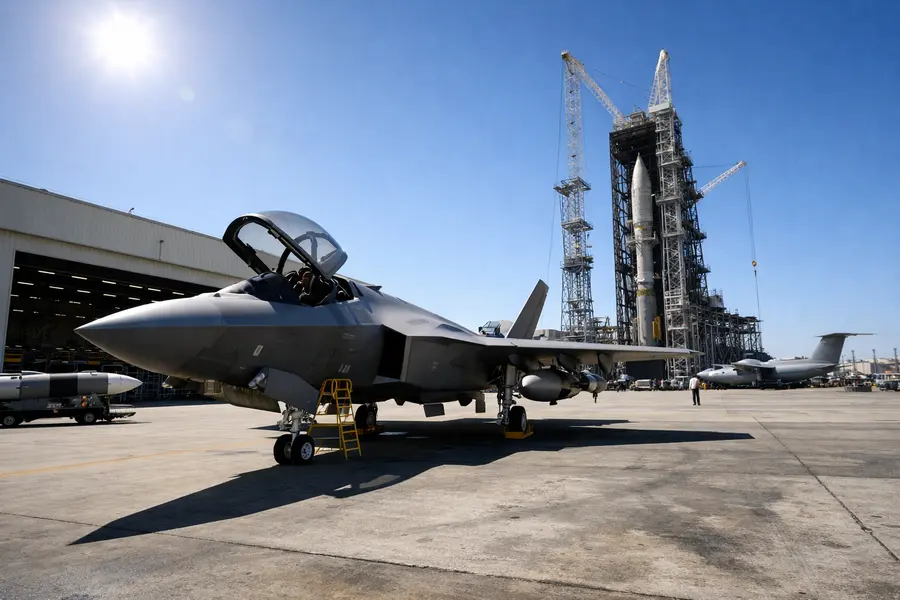
Lockheed Martin (LMT) beat third-quarter estimates, reached a record $292 billion backlog and raised its 2026 outlook, sending shares up about 9% and lifting defense peers.
Kim Jong Un's surprise day trip over the New Yalu River Bridge to Dandong shows Beijing moving to reclaim influence over North Korea from Moscow as trade rises.
Russia agreed in principle to resume three-way talks with Kyiv and Washington, then fired 21 ballistic missiles at Kyiv within hours, as Brent held near $114.
Markets price over a 60% chance the RBA lifts interest rates to 4.85% on Nov. 3, up from under 20% a week ago, after a deputy governor's inflation warning.
Surgery Partners stock surged about 21% premarket as Bon Secours Mercy Health neared a roughly $6B majority-stake deal, including debt, for the Bain-backed chain.
Brazilian ADRs plunged premarket Monday after Lula won a fourth term with 51.8% of the vote; Petrobras fell about 21%, Itaú about 26% and Ambev about 19%.
Russia and Ukraine agreed a temporary local ceasefire in occupied Oleshky for humanitarian aid and civilian evacuation, brokered by Melania Trump, the White House says.
Bitcoin slipped under $80,000 on October 26, testing the floor of a $80K-$86K range as traders de-risk before the Federal Reserve's October 28 decision.
US revises its 50% tariff list on Canadian goods from Oct. 30 as Hassett calls a trade deal very close, though Ottawa expects no pact before Nov. 3.
Gold is trying to steady near $4,000 and silver near $54 an ounce after a rough week, as high Treasury yields and Fed hike bets weigh on non-yielding metals.
The 10-year Treasury yield slid below 5% on Oct. 22 after peaking at 5.36%, as an AI-led stock sell-off drove investors into bonds and lowered interest rates.
CoreWeave (CRWV) shares are down about 30% in October as a $50 billion debt load and bond yields above 15% raise doubts over AI infrastructure funding.
Microsoft, Alphabet and Amazon report as the Fed decides on rates Wednesday, with PCE data due Thursday and midterms on Nov. 3 shaping the stock market today.
American Express (AXP) fell more than 3% after it said it will cut about 5% of its global workforce to prepare for AI, even as it raised its 2026 earnings outlook.
SpaceX (SPCX) beat Q3 2026 estimates with $14.6B in revenue, up 161%, but a tech sell-off left the stock up only about 1% for the week despite Musk's $1T target.
The Federal Reserve is set to hold rates at 3.75%-4.00% on Oct. 28, but oil near $117 and 3.7% inflation have futures pricing a December hike at about 70%.
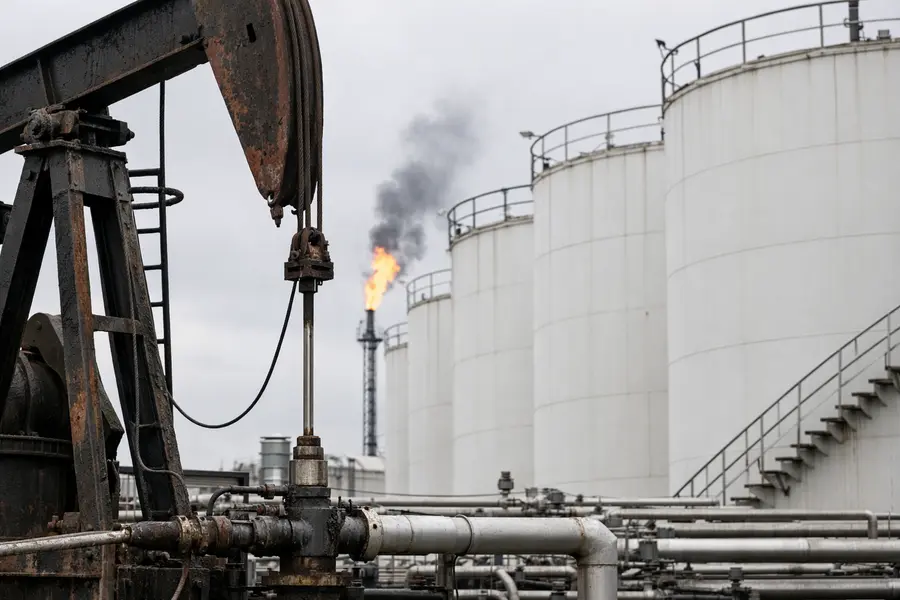
Brent crude settled at $116.72 a barrel, its highest close in six months, as Red Sea attacks and reported US-Israeli strike plans on Iran tightened oil supply fears.
Nasdaq Meta (META) fell about 7% after Q3 2026 results showed record AI spending and negative free cash flow. A new nonvoting share class also unsettled the market.