Pomegra
TD SYNNEX reports fiscal Q3 results before the bell September 24, with consensus at $4.70 EPS and $18.91B revenue — the sharpest real-world test of whether enterprise AI hardware is shipping at scale.
- Consensus non-GAAP EPS of $4.70 implies 31% year-over-year growth; revenue of $18.91B implies 21% growth for the quarter ended August 31, 2026.
- Hyve Solutions, TD SYNNEX's hyperscaler manufacturing arm, posted $5.5 billion in gross billings in Q2 — up 117% year-over-year — making Q3 a critical confirmation test.
- SNX has beaten the Zacks consensus in each of the trailing four quarters at an average surprise of 21.7%, sustaining a high bar heading into Thursday's print.
Lead
TD SYNNEX Corporation (SNX) releases its fiscal third-quarter 2026 results before the opening bell on September 24, with Wall Street's consensus penciling in non-GAAP earnings per share of $4.70 -- a 31% increase over the year-ago period -- on revenue of $18.91 billion, up 21% year-over-year, for the quarter ended August 31, 2026. The print carries unusual weight beyond the company itself. As the world's largest IT products distributor and a direct contract manufacturer to every major U.S. hyperscaler through its Hyve Solutions unit, TD SYNNEX sits at the intersection of every significant AI infrastructure supply chain in operation today. Its quarterly numbers constitute the cleanest public read on whether the wave of enterprise AI hardware commitments announced throughout 2025 and early 2026 is clearing warehouses and data-center loading docks -- or still waiting to ship.What Makes This Quarter a Bellwether for AI Stocks?
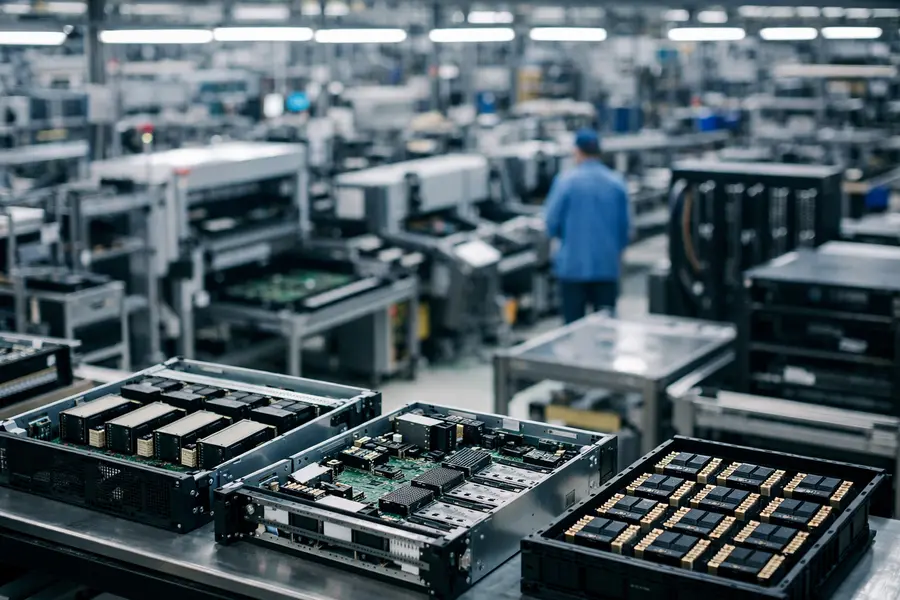
The answer is Hyve Solutions. TD SYNNEX's custom compute manufacturing division partners directly with cloud-platform operators to design and build accelerated-compute infrastructure, including the GPU server racks and networking gear that underpin large-scale AI workloads. In Q2 FY2026, Hyve posted gross billings of $5.5 billion -- a 117% year-over-year surge -- with manufacturing representing approximately two-thirds of that activity. The company holds program wins across all five U.S.-based hyperscalers, with CEO Patrick Zammit citing "AI-driven infrastructure investment" as the central organizing force behind both the Hyve and Distribution segments. A similarly strong Q3 Hyve reading would confirm that hyperscaler capital expenditure for AI is translating into actual hardware throughput, not just announced spending intentions. A sequential deceleration would raise questions about order timing, supply constraints, or a plateauing of near-term build-out intensity.
How Does the Distribution Segment Fit the Story?
Beyond Hyve, TD SYNNEX's broader distribution business serves more than 150,000 enterprise and commercial customers across 100-plus countries, channeling compute, networking, cybersecurity, and cloud-software products from the full roster of technology vendors. Demand across that segment has broadened materially over the past year. Modernization cycles in PCs, edge compute, and software, alongside persistent growth in cybersecurity deployments, have added volume across the channel. TD SYNNEX was also selected as one of only two global distribution partners by Hewlett Packard Enterprise (HPE) for its networking, cloud, and AI portfolios -- a concentration of vendor relationships that reinforces its position as the intermediary capturing the most diversified share of enterprise technology refresh. Combined, the two segments make SNX a composite signal: Hyve reads hyperscaler capital intensity; Distribution reads broad enterprise IT appetite.
Guidance Range and Street Estimates
Management set Q3 guidance in June at non-GAAP EPS of $4.25 to $4.75 -- a midpoint of $4.50 -- and revenue of $18.2 billion to $19.0 billion. The Street's consensus of $4.70 sits comfortably near the top of that range, reflecting the market's expectation that TD SYNNEX will, as it has in each prior quarter, close toward or above its own high-end projections. Gross billings guidance for Q3 was set at $27.2 billion to $28.2 billion, compared with $28.9 billion in the prior quarter. The modest sequential step-down in billings reflects typical seasonality in the late-summer period as well as product-mix variability in Hyve, where program ramps are lumpy by nature. Additional Hyve program ramps were flagged for late fiscal 2026 and early fiscal 2027, underscoring that the Q3 result is as much a setup reading as it is a stand-alone data point.
Why Did the Stock Run Into Earnings?
SNX shares have gained approximately 18% over the past month and more than 106% over the trailing twelve months, closing the prior session at roughly $283. That run compresses the implicit bar the company must clear for the stock to hold gains. The bull case rests on continued above-guidance execution: in Q2, revenue of $19.6 billion beat the $16.84 billion Zacks consensus by 16.2%, and non-GAAP EPS of $4.85 exceeded the $4.11 estimate by $0.74 -- one of the cleaner beats recorded in the technology distribution space that quarter. If Q3 follows that pattern, the focus will shift immediately to Q4 guidance and whether management upgrades the range to incorporate the next tranche of Hyve program ramps. Analysts have issued 11 positive EPS revisions and zero negative revisions in the 90 days leading to Thursday's report -- a posture that reflects confidence, but also leaves limited room for ambiguity.
How Should Investors Read the Margin Lines?
Operating margins are the secondary test. In Q2, non-GAAP operating margin expanded 37 basis points to 3.14%, even as Hyve's product mix compressed segment-level margins due to supply-chain variability. Management characterized the distribution margin gain as partially temporary, tied to inventory positioning, which means Q3 margin performance will be read against a more normalized base. A stable or modestly expanding non-GAAP operating margin in Q3 would confirm that Hyve's scale is beginning to offset its inherent volatility -- an important signal for those evaluating whether the AI hardware distribution model generates durable earnings leverage or simply top-line volume.
Outlook
The September 24 TD SYNNEX earnings call -- beginning at 9:00 a.m. ET -- arrives as one of the most consequential near-term data points in the technology hardware calendar. Whether SNX meets the $4.70 EPS and $18.91 billion revenue marks, and how the Hyve segment performs relative to its Q2 trajectory, will shape the near-term narrative around whether the AI infrastructure buildout is in full commercial delivery mode or entering a digestion phase. Q4 guidance, and any commentary on the timing and scale of next-generation Hyve program ramps, will determine whether the stock's 106% annual run carries a defensible forward earnings foundation or begins to discount a more gradual growth path through fiscal 2027.