Pomegra
Lennar's Q3 EPS miss and 9.2% new-order decline prompt a FY26 delivery cut to 80,000-81,000 homes, confirming 7% mortgage rates have strangled housing demand.
- Lennar (LEN) posted Q3 EPS of $0.23, missing the $0.29 consensus as mortgage-rate pressure compressed closings and margins.
- New home orders fell 9.2% year-over-year to 20,879 units, the deepest quarterly contraction of the current rate-driven downturn.
- Lennar cut its FY26 delivery target to 80,000-81,000 homes, signaling management sees no demand recovery before year-end.
Lead
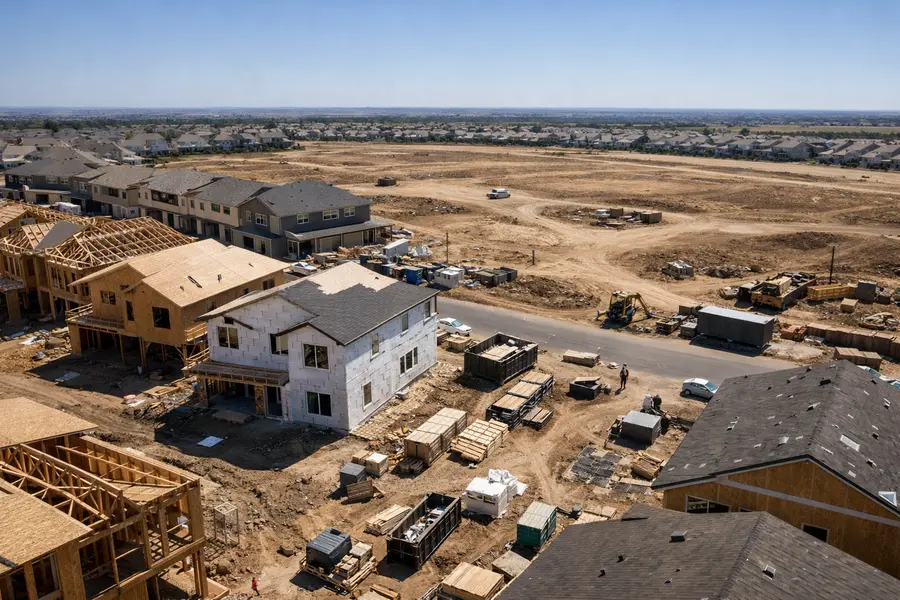
Lennar Corporation (LEN), the nation's second-largest homebuilder by volume, reported third-quarter 2026 results that missed Wall Street expectations across every major metric, as mortgage rates entrenched near 7% continued to suppress buyer demand in a residential market that has yet to find a floor. Earnings per share of $0.23 came in below the $0.29 consensus estimate, while quarterly revenue of approximately $8.05 billion fell roughly $280 million short of the $8.33 billion projection. Lennar simultaneously trimmed its full-year 2026 home delivery target to 80,000-81,000 units, down from a prior range that implied output in the mid-to-upper 80,000s, confirming that affordability constraints have shifted from a cyclical headwind into a structural drag on volume and margins.Why Did New Orders Fall 9.2%?
New home orders declined 9.2% year-over-year to 20,879 homes in the quarter, the steepest contraction Lennar has recorded in this rate cycle, because persistent interest rates near 7% have priced out a wide swath of qualified buyers. Monthly payments on a median-priced new home at current financing costs have climbed far above the thresholds that allow middle-income households in major markets to clear standard debt-to-income hurdles. Cancellation rates remained elevated as buyers who entered contracts under earlier rate assumptions walked away once rate locks expired unfavorably, further hollowing out the backlog that sustained builders through the 2021-2023 construction boom.
What Went Wrong on EPS and Revenue?
The $0.06 per-share shortfall reflects a dual hit: fewer closings and narrower gross margins, as Lennar leaned on mortgage rate buydowns and price concessions to move standing inventory in markets where organic demand has softened materially. Revenue fell approximately $280 million short of consensus, a gap driven by reduced delivery volume rather than a collapse in average selling prices - Lennar's average selling price held in the mid-$400,000 range but could not absorb the volume shortfall. The incentive burden required to sustain even that level of activity compressed margins in a quarter when operating leverage works against builders at lower throughput.
Housing Market Context
The Lennar miss lands against a backdrop of broad residential real estate strain. Existing home sales have remained near three-decade lows as the lock-in effect - owners carrying sub-3% mortgages unwilling to refinance into a 7% environment - has compressed resale inventory and channeled residual demand toward new construction. That pipeline of buyers, already narrowed, is now thinning further as affordability deteriorates. Even aggressive builder incentives offering one-percentage-point buydowns leave monthly costs well above median-income thresholds in high-cost metros. The Federal Reserve's path on interest rates remains the single most consequential variable for the sector's recovery timeline.
How Does Lennar's Guidance Cut Signal Sector Risk?
The revised FY26 delivery target of 80,000-81,000 homes implies a second-half trajectory materially weaker than the first and sets a lower ceiling for what was already a subdued year. For peers, the revision functions as a leading indicator: D.R. Horton (DHI) and PulteGroup (PHM) face comparable demand dynamics in their forthcoming reports, and both carry guidance ranges that may require similar trimming. Investors in SPDR S&P Homebuilders ETF (XHB) and adjacent positions have absorbed compounding guidance risk through 2026, and Lennar's cut sharpens the question of whether current consensus estimates for the full homebuilding sector have caught up to the rate reality that Lennar's results make explicit.
Outlook
Lennar's Q3 2026 results remove ambiguity about where the housing market stands: demand is contracting, not stabilizing, and the revised FY26 delivery target of 80,000-81,000 homes is the clearest signal yet that no near-term recovery is priced into management's expectations. Without a sustained decline in long-term interest rates driven by Federal Reserve easing or a meaningful compression in Treasury term premiums, demand conditions are unlikely to improve materially through early 2027. The sector faces a prolonged period of guidance risk, margin compression, and downward earnings revisions - with the pace and depth of any Fed pivot now functioning as the primary catalyst watch for homebuilder shareholders.
Mentioned tickers: LEN, DHI, PHM, XHB