Pomegra
Micron Technology (MU) reports fiscal Q4 2026 earnings Tuesday with $50 billion in revenue on the line, putting the AI memory supercycle's durability to its most consequential test yet.
- MU guided Q4 FY2026 revenue to $50 billion at midpoint, with gross margin near 86% and non-GAAP EPS of $31.
- Shares have gained 276% year-to-date, crossing a $1 trillion market capitalization in May 2026.
- HBM4 shipments surpassed $1 billion in revenue ahead of schedule, with supply fully contracted through year-end.
Lead
Micron Technology (MU) reports fiscal fourth-quarter 2026 results after the closing bell on September 30, with the midpoint of company guidance calling for $50 billion in revenue - a figure more than tenfold above the same period two years prior. The company enters the print with micron technology stock up 276% year-to-date, a balance sheet transformed by AI-driven pricing power, and a market watching for confirmation that the memory sector's structural reset is permanent, not cyclical.Why Is Micron the AI Earnings Catalyst of the Week?
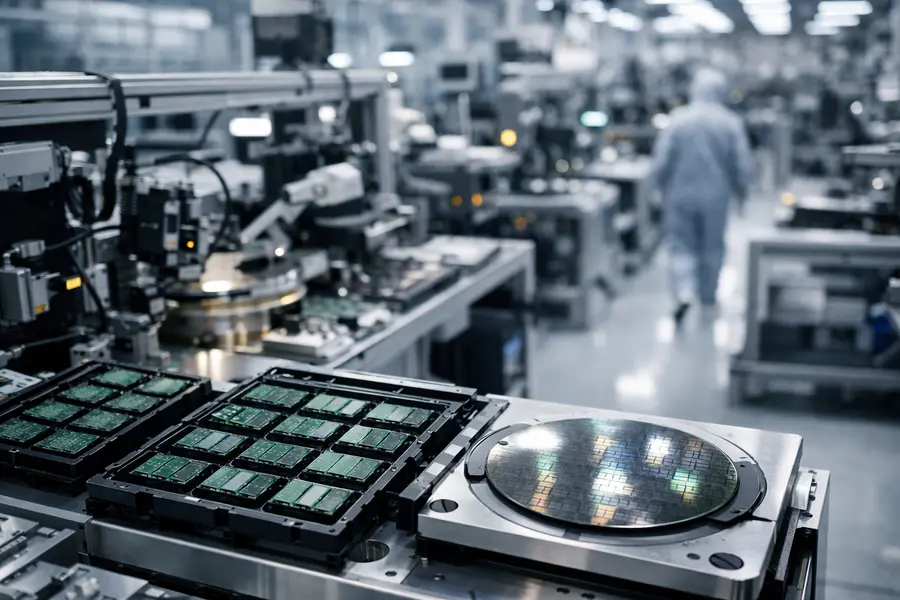
Micron sits at the intersection of two structural forces reshaping global technology spending: surging hyperscaler capital expenditure on AI infrastructure and a supply-constrained market for high-bandwidth memory. The company is the primary U.S. manufacturer of HBM chips - the specialized DRAM that powers the most advanced AI accelerators from NVIDIA (NVDA) and other platform operators. Management has stated HBM demand for 2027 and 2028 already outstrips the company's supply capacity, and its HBM4 product is ramping at twice the pace of its HBM3E predecessor. Sixteen Strategic Customer Agreements, spanning approximately five years and representing roughly $100 billion in committed cumulative revenues, underpin the case that this upcycle carries unusual structural depth.
The Numbers Behind the 276% Rally
The scale of Micron's financial transformation frames Tuesday's report as more than a routine earnings event. For the nine months ending May 2026, total revenue surged 203% against the comparable prior-year period. DRAM average selling prices rose approximately 140% while bit shipments grew roughly 30%; NAND prices climbed 130% alongside low-20% volume gains. Fourth-quarter guidance sets gross margin at approximately 86% - a level historically unthinkable for a commodity memory producer - with non-GAAP EPS of $31 against $3.03 a year earlier. Adjusted free cash flow for Q4 is projected to exceed $30 billion, redefining what the market is willing to pay for MU.
What Comes Next for AI Stocks If Micron Beats?
A beat-and-raise outcome would represent one of the clearest signals yet that AI infrastructure spending is a multi-year structural commitment, not a single-year capital surge. Micron's supply constraints are structural: clean-room economics, the capital intensity of HBM4 production stacks, and long-term binding contracts make a rapid supply response unlikely before 2027. The company has committed to a $100 billion manufacturing complex in Syracuse, New York, both as a confidence signal and as a strategic move to narrow the gap with Samsung Electronics and SK Hynix in domestic AI chip capacity. The broader semiconductor sector - tracked through SOXL and the SMH ETF - trades closely to Micron's quarterly prints, amplifying the report's market-wide significance.
Competitive Position: HBM4 and the Race With SK Hynix
Samsung and SK Hynix retain larger aggregate HBM market shares, but Micron is closing ground faster than the prior product cycle suggested. HBM4 12-high stacks are ramping at twice the pace of HBM3E, and Micron became the first memory manufacturer to cross $1 billion in HBM4 revenues ahead of its own timeline. Strategic customers have locked in multi-year pricing agreements, a structural shift that differentiates this cycle from the volatile spot-market dynamics that historically drove DRAM sector earnings swings. That pricing visibility is the central reason Wall Street has lifted MU price targets into the $1,200-$1,500 range, with consensus projecting the memory upcycle running another five to six quarters.Outlook
Micron enters fiscal Q4 2026 earnings with $50 billion in guided revenue, near-record gross margins, and a stock that has returned 276% in calendar 2026. The AI memory supercycle thesis now faces its most substantive verification event to date. Fiscal year 2027 guidance will carry equal weight: whether hyperscaler demand holds as global AI deployment matures from initial buildout into optimization will determine whether the memory sector's structural profitability reset endures. The answer arrives after the close on September 30.