Pomegra
Carnival (CCL) matched Q3 EPS of $0.35, but unhedged exposure to $105 Brent crude and a 25% year-to-date stock decline raise serious questions about the dividend's sustainability.
- Carnival reported Q3 2026 EPS of $0.35, matching analyst consensus, while CCL shares remain more than 25% below their January 2026 open
- Brent crude near $105 per barrel - up 45% above pre-Iran-conflict levels - hits an unhedged Carnival directly on its largest variable cost line
- Rising fuel costs are narrowing the free cash flow margin available for the reinstated dividend, sharpening capital allocation pressure
Lead
Carnival Corporation (CCL), the world's largest cruise operator, posted third-quarter 2026 earnings per share of $0.35 on Monday, matching the Wall Street consensus. The in-line result provided investors little relief. Brent crude has surged approximately 45% above pre-war levels to around $105 per barrel on Iran conflict supply disruptions, and Carnival carries no active fuel hedges - a gap that flows directly into operating margin compression across all three of the company's major brand segments. CCL has shed more than 25% of its market value year-to-date.
Why Is CCL Down 25% Despite Hitting the EPS Target?
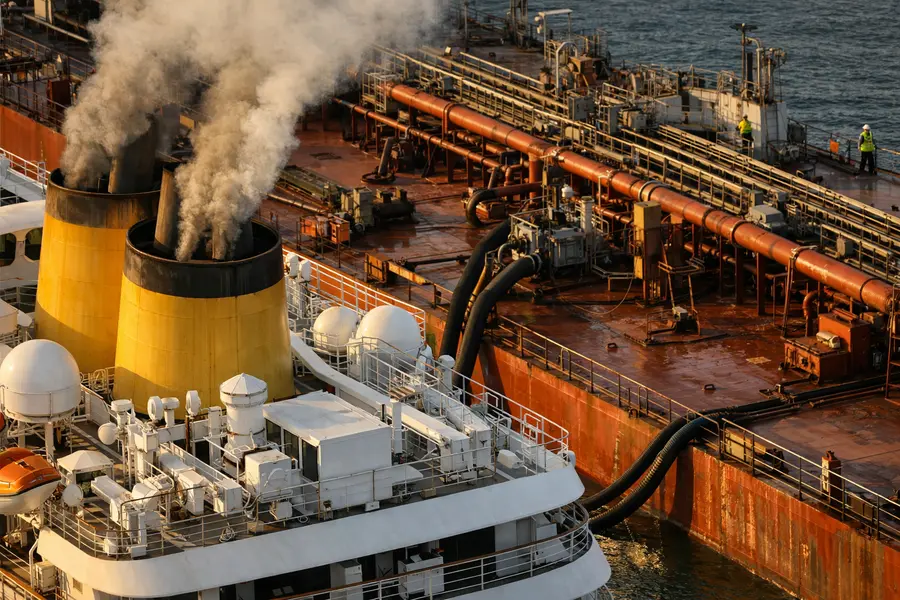
Matching consensus offers limited support when the forward cost structure is deteriorating faster than revenue growth can absorb. Fuel typically represents 12 to 14 percent of Carnival's total operating expenses; at current crude levels, each $10-per-barrel move in Brent adds hundreds of millions of dollars to the company's annualized cost base with nothing in place to offset it. Carnival has maintained no active fuel hedging positions - a contrast to several airline and energy-intensive peers that locked in coverage when Brent was below $75. Investors have repriced CCL shares accordingly, with the stock now trading at its steepest discount to pre-conflict valuations in three years.
The Iran Supply Shock and Crude Oil Prices
The crude oil price surge originates in cascading supply disruptions linked to the Iran conflict. Tanker transit through the Strait of Hormuz - which handles roughly 20 percent of global seaborne crude - has been intermittently constrained, tightening the global balance and pushing Brent back above $100 per barrel for the first time since mid-2023. Prices near $105 have proven more durable than early market estimates suggested, as diplomatic efforts toward a ceasefire have repeatedly stalled.
For Carnival, the timing compounds a multi-year balance sheet challenge. The company rebuilt fleet utilization to near pre-pandemic levels and was on a path toward sustained free cash flow recovery. The Iran-driven energy shock arrived before management had restored enough balance sheet flexibility to absorb a prolonged cost spike without revisiting capital return priorities.
What Does Carnival's Unhedged Fuel Position Mean for Full-Year Margins?
The absence of hedging means Carnival absorbs crude oil price movements with no financial offset. Adjusted cruise operating margins, which had been rebuilding toward management's 15 to 17 percent target range for fiscal 2026, now face pressure from two directions: fuel costs rising well above guidance assumptions, and the potential for discretionary travel spending to soften if broad consumer budgets tighten under sustained high energy prices. The Q3 earnings call is expected to deliver updated full-year fuel cost guidance and may signal whether Carnival intends to establish any hedging coverage heading into fiscal 2027.
Is the Carnival Dividend Sustainable?
Carnival reinstated its dividend in 2024 as part of a capital return framework tied to specific leverage reduction and free cash flow thresholds. With Brent near $105 and no hedging limiting downside exposure, the free cash flow margin available for dividend payments has narrowed materially. Sustained crude above $100 per barrel through a second consecutive fiscal quarter would place the company in a position where dividend maintenance and accelerated debt paydown become competing priorities. Management has not signaled a reduction, but the capital allocation discussion on Monday's earnings call is likely to draw significant scrutiny.
Outlook
Carnival's Q3 result confirms that passenger demand and pricing power remain intact for the cruise sector. The central challenge for the remainder of fiscal 2026 is the widening gap between stable revenue and an uncontrolled fuel cost line exposed to geopolitical risk. Whether Brent crude retreats from the $105 level - and how quickly - will determine whether the dividend is maintained and whether the 25%-plus year-to-date decline in CCL stabilizes or extends into year-end.