Pomegra
Industrial output rose 0.7% in September and manufacturing capacity use hit 75.9%, the highest since early 2024, lifting S&P 500 futures.
- Industrial production gained 0.7% in September, well above the 0.4% forecast, after a revised 0.1% rise in August.
- Total capacity utilization rose to 76.9%, the highest since December 2023, with manufacturing at 75.9%.
- S&P 500 futures rose about 0.5% and Nasdaq 100 futures about 0.9% as the data eased growth concerns.
Lead
US industrial production rose 0.7% in September, the Federal Reserve reported on October 16, beating the 0.4% forecast and marking the strongest monthly gain in the recent run of data. Manufacturing capacity utilization climbed to 75.9%, its firmest reading since early 2024, while the broader industrial rate reached 76.9%. The report gave S&P 500 futures a lift on Tuesday and eased concerns that the economy was losing momentum.
What Did the September Industrial Production Report Show?
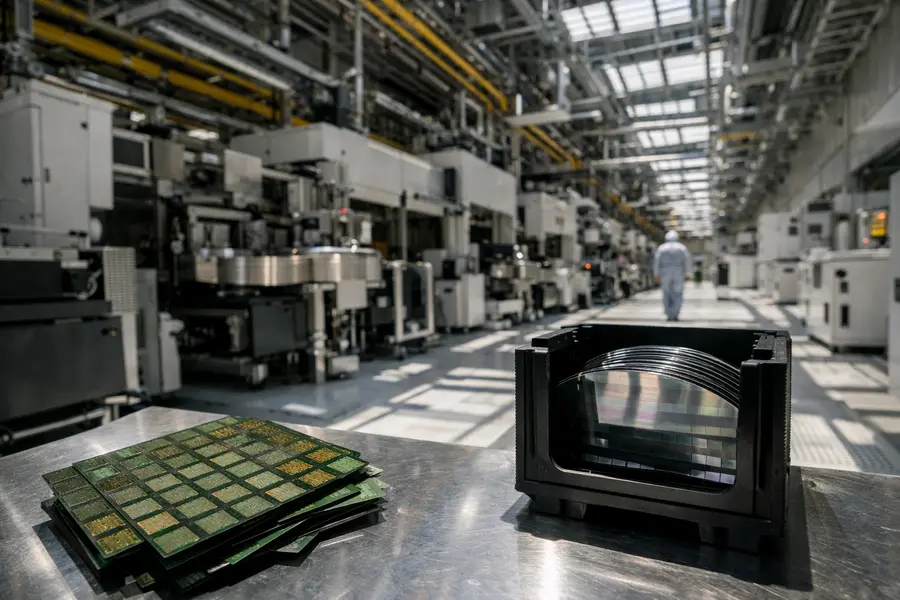
The report showed output rising across every major category, led by utilities. Utilities output jumped 3.5%, manufacturing rose 0.3% after a 0.2% decline in August, and mining edged up 0.2%. August industrial output was revised up to a 0.1% gain.
Capacity utilization, which measures the share of industrial capacity in use, rose to 76.9% from an upwardly revised 76.4% in August. That is the highest level since December 2023 and above the 76.5% forecast. By sector, mining ran at 87.5%, utilities at 73.8% and manufacturing at 75.9%.
The headline figure leaned on weather-sensitive utilities. Even so, the factory rebound after August's decline suggests the goods-producing economy is firming rather than stalling.
Why Did S&P 500 Futures Rise?
Futures rose because the data pointed to firmer corporate demand and pricing power heading into a heavy earnings week. S&P 500 futures gained about 0.5% and Nasdaq 100 futures about 0.9% on Tuesday. Investors read higher utilization as a sign that producers can hold prices and support revenue.
The bounce followed a weak Friday, when the release landed on a day of technology-led selling. The S&P 500 fell 1.1% to 7,659, the Nasdaq Composite dropped 2.1% to 26,140 and the Dow Jones Industrial Average slipped 0.3% to 52,002. The strong industrial data did not stop that decline, but it gave buyers a reason to return when trading resumed.
Exchange-traded funds tracking the benchmarks, including SPY and QQQ, followed the futures higher in early indications.
What Does Stronger Factory Activity Mean for Interest Rates?
Stronger factory activity complicates the outlook for interest rates because it supports growth while adding to inflation risk. Tighter capacity can push producers to raise prices, and bond markets can respond by pricing in a stickier path for inflation. That would raise yields and borrowing costs, which weigh on equity valuations.
This sets up a tension for the federal reserve. Firm output reduces the case for policy support aimed at a slowing economy. It also gives policymakers less reason to hurry further easing if price pressures stay elevated. A utilization rate of 76.9% remains below the long-run average of roughly 79%, which leaves room for output to expand before capacity constraints become a major source of inflation.
Market Reaction
Equity futures were the clearest beneficiary. Sectors tied to the domestic industrial cycle, including machinery, materials and utilities, stand to gain most from firmer output and utilization. Technology shares, which drove Friday's decline, remain sensitive to any rise in Treasury yields.
The earnings calendar will be the next test. Corporate results this week will show whether the improvement in output translates into stronger order books, margins and guidance, or whether the September gain reflects one-off factors such as weather-driven utility demand.
What Comes Next for the US Economy?
The next signals come from regional manufacturing surveys, the October jobs data and the next inflation readings. Each will show whether the September rebound in factory output is sustained. A second consecutive gain in manufacturing would confirm that the August dip was temporary. A fall back in utilities output would reduce the headline strength and leave the manufacturing figure as the main indicator of underlying demand.
Two scenarios frame the near term. If output and utilization keep rising while inflation holds steady, the data supports a soft landing and a steady equity market. If utilization climbs alongside rising prices, bond yields could rise and pressure stock valuations, particularly in growth sectors.
Outlook
September's 0.7% gain in industrial production and the rise in capacity utilization to 76.9% point to a stronger industrial base than markets had expected. Manufacturing utilization of 75.9% is the best since early 2024. The data eased growth fears and supported S&P 500 futures, though the effect on yields and Fed policy will determine whether the improvement carries into the rest of the quarter.
Mentioned tickers: SPY, QQQ