Pomegra
Maersk, Hapag-Lloyd and CMA CGM suspend Strait of Hormuz transits after Iranian drones strike two more tankers, pushing war-risk insurance premiums to record highs.
- Iranian drone fire struck two commercial tankers near the Strait of Hormuz over the weekend, escalating the US-Iran maritime conflict to a new threshold.
- Maersk (MAERSK-B), Hapag-Lloyd (HLAG), and CMA CGM announced full transit suspensions, rerouting fleets around the Cape of Good Hope.
- War-risk insurance premiums for Hormuz passage surged to their highest level on record, adding hundreds of thousands of dollars per vessel per voyage.
Lead
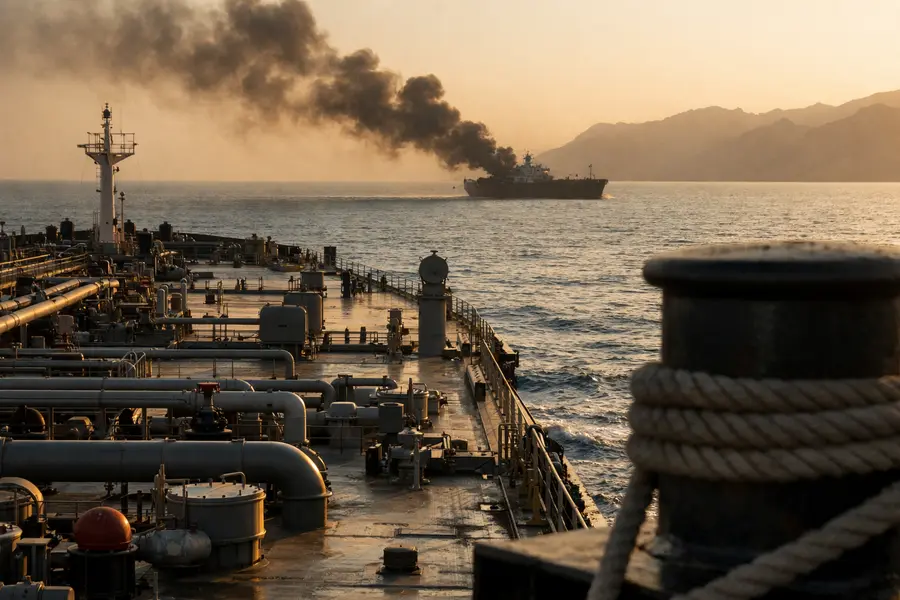
Two commercial tankers were struck by Iranian drone fire near the Strait of Hormuz over the weekend, prompting the three largest container shipping groups on earth to halt all future passage through the waterway that carries an estimated 20 percent of global seaborne oil. Maersk (MAERSK-B), Hapag-Lloyd (HLAG), and privately held CMA CGM announced transit suspensions within hours of each other on Sunday, triggering a fresh surge in crude oil prices and sending war-risk insurance premiums to their highest recorded levels. The US-Iran tanker war, which has now claimed at least a dozen vessels in attacks spanning several weeks, showed no sign of de-escalating.
What Triggered the Shipping Freeze?
The weekend drone strikes - the second concentrated attack wave in under two weeks - were the direct catalyst for the carriers' decisions. Iranian forces targeted two unnamed commercial tankers operating in waters approaching the Strait's eastern corridor, causing significant hull damage and prompting emergency evacuations of crew in at least one case. Neither vessel sank, but the precision and scale of the strikes demonstrated an expanded Iranian drone capability that US naval assets in the region have so far been unable to reliably intercept. For Maersk, Hapag-Lloyd, and CMA CGM, the risk calculus crossed a threshold that made continued transit commercially and legally untenable.
Why Are War-Risk Insurance Premiums at Record Highs?
War-risk premiums for Hormuz transits reached their highest level on record following Sunday's strikes, with specialist underwriters pricing single-voyage cover at rates adding an estimated $500,000 to $800,000 per passage for large crude carriers. The Lloyd's of London market and major war-risk pools have designated the full eastern Arabian Gulf approach as an elevated-risk zone, triggering mandatory notification clauses that bind hull and cargo underwriters worldwide. The surge reflects two compounding factors: the demonstrated lethality and unpredictability of Iranian one-way attack drones, and thinning US naval capacity to provide credible deterrence across the entire strait corridor. For vessel operators who might otherwise accept the physical risk, the insurance cost alone renders transit economically prohibitive.
Strategic and Economic Ripple Effects
Rerouting around the Cape of Good Hope extends voyage times between the Persian Gulf and European or East Asian ports by an estimated 14 to 18 days. The freight-rate consequences are immediate. Spot container rates on Asia-Europe and Asia-Mediterranean lanes, already elevated from the preceding Red Sea crisis, face a fresh leg higher as carriers absorb longer steaming distances, higher bunker fuel consumption, and additional port-time costs. For global supply chains still digesting the Red Sea episode's inflationary aftershocks, the Hormuz closure compounds cost pressure at a critical moment.
How Does This Affect Global Energy Supply?
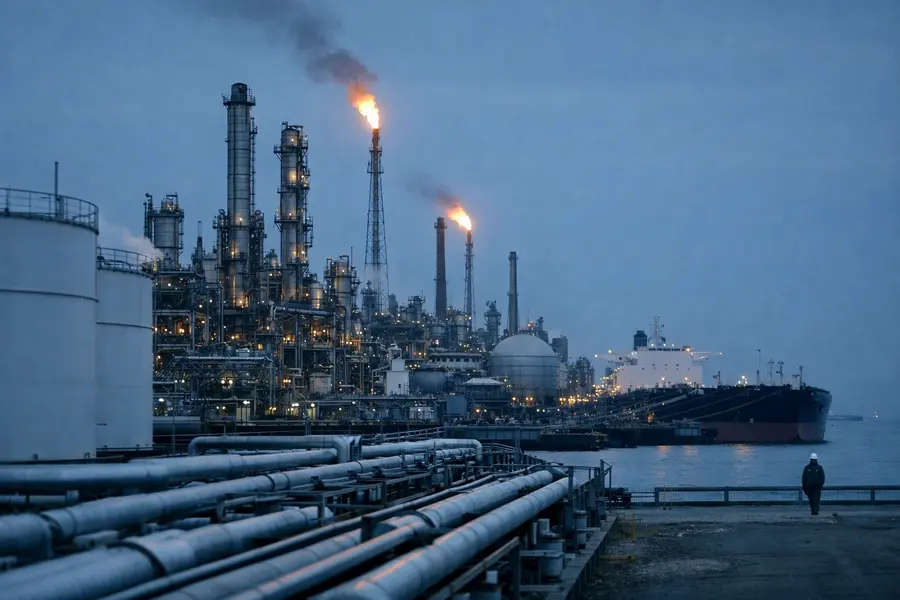
The Strait of Hormuz remains the world's most concentrated oil transit chokepoint, with 17 to 21 million barrels per day flowing through under normal conditions. The immediate threat is not to raw volume - national oil companies and dedicated tanker operators are still assessing their own risk postures independently of the container carriers - but to the availability of insurance cover and qualified crew willing to transit. If war-risk underwriters withdraw capacity entirely, even operators prepared to accept physical risk may find transit commercially or legally impossible. Gulf producers are in emergency discussions about maximizing pipeline bypass capacity: the UAE's Abu Dhabi Crude Oil Pipeline, capable of moving up to 1.5 million barrels per day to the Fujairah terminal on the Gulf of Oman, bypasses the strait entirely and is expected to operate at full capacity in the coming days.
Geopolitical Dimension
Tehran's continued strikes signal that Iran's maritime pressure campaign has not moderated despite intermittent diplomatic contacts with Washington. The Pentagon has deployed additional naval assets to the region and has not ruled out retaliatory strikes against Iranian drone production and launch infrastructure. The conflict has drawn in non-Western powers economically dependent on unimpeded Gulf energy flows, creating new diplomatic pressure on Tehran from capitals that had previously sought neutrality. A credible multilateral deterrence framework - absent so far - remains the most plausible structural off-ramp.
Outlook
With three of the world's largest carriers now absent from the Hormuz corridor, the strategic stakes of de-escalation have risen to their highest point since the conflict began. War-risk insurance markets will remain under acute pressure until credible security guarantees or a ceasefire arrangement emerges. Freight rates on long-haul routes are poised to climb further as the rerouting effect compounds through the fourth quarter. Energy markets will track the crude oil price closely as the full scope of supply-route disruption becomes clear. The absence of any near-term diplomatic framework means the shipping industry, oil markets, and the broader global economy face a sustained period of elevated costs and geopolitical uncertainty.
Mentioned tickers: MAERSK-B, HLAG