Pomegra
France's weekend riots and nearly 2,400 arrests pushed the 10-year yield to 4.86% and the CAC 40 down 1.2%, as markets watch the 2027 budget vote closely.
- Nearly 2,400 people were arrested after cost-of-living protests turned violent across France on October 17.
- The 10-year OAT yield rose to about 4.86% and the CAC 40 fell about 1.2%.
- The 2027 budget, targeting a 5.0% of GDP deficit, is the next test for investors.
Lead
French assets sold off on Monday, October 19, after a weekend of rioting over living costs left nearly 2,400 people under arrest. The benchmark 10-year government bond yield rose to about 4.86% and the CAC 40 fell about 1.2%. Financial markets today are pricing a simple question: can the government pass a 2027 budget that cuts the deficit while social anger is rising?
What Happened in France Over the Weekend?
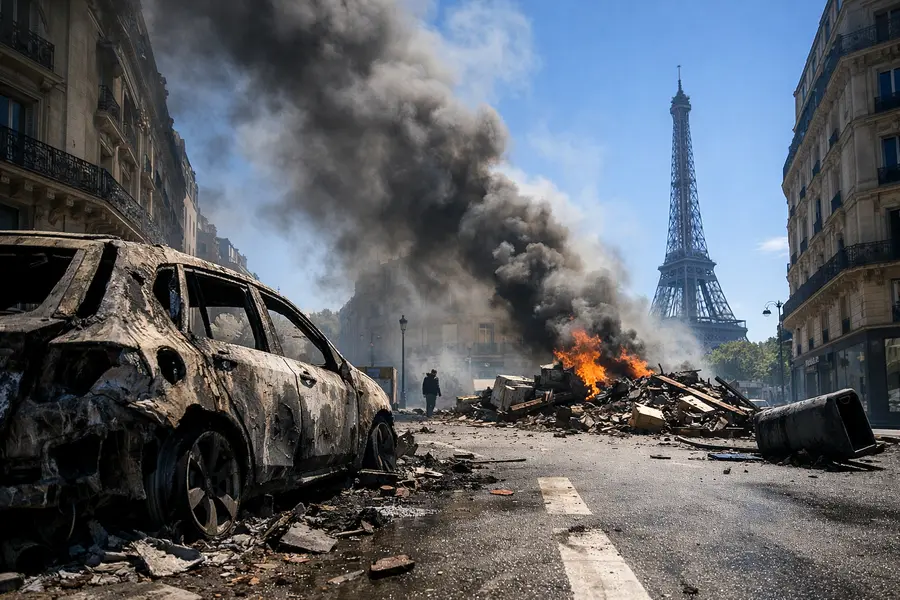
Nationwide demonstrations over the cost of living on October 17 escalated into looting, arson and clashes with police. Authorities counted about 550,000 participants nationwide, while organizers put the figure near 800,000.
Almost 1,000 police officers and firefighters were injured. Rioters ransacked storefronts and set fire to municipal buildings. In Limoges, a deliberately set fire nearly destroyed the 19th-century city hall. President Emmanuel Macron vowed to hold accountable those who sought to bring down the Republic.
The scale of the arrests, close to 2,400, makes this one of the most serious bouts of unrest in France in recent years. Previous episodes, including the 2018 yellow vest protests and the 2023 riots, also followed disputes over living standards and policing.
Why Did French Bonds and the CAC 40 Fall?
French bonds and equities fell because the unrest raised the odds that lawmakers will dilute or fail to pass the deficit-reduction plan. That would leave France with the largest debt burden among its major euro peers and little fiscal room to absorb it.
The 10-year OAT yield, the return on France's benchmark government bond, rose to about 4.86%. Prices fall as yields rise, so the move reflects selling in French debt. The gap to German 10-year Bund yields stood at about 142 basis points on October 19. That is close to the roughly 150 basis points reached on October 2, the widest since 2012. A wider spread means investors demand more compensation for holding French rather than German risk.
The equity move was smaller but broad-based. The CAC 40 lost about 1.2% in early trade. Investor positioning toward French stocks was already at a record underweight before the weekend, which limits how much further some funds can reduce exposure.
Higher borrowing costs matter beyond the bond market. The French state's debt rose from 98% of GDP in 2019 to above 119% in the second quarter of 2026, and it is projected to pass 121% in 2027, against roughly 83% to 87% for the euro area. Each increase in interest rates feeds directly into the interest bill, which competes with the spending the government is trying to restrain.
Can the Government Pass the 2027 Budget?
Passing the 2027 budget is possible but depends on a fragmented parliament that has already toppled governments over fiscal plans. The draft, presented on October 1, targets a public deficit of 5.0% of GDP in 2027, down from 5.4% this year, through a package of spending restraint and new revenue measures.
Three routes are open to the executive:
- Negotiated passage. A compromise in the National Assembly would reassure investors most. It would also require concessions to parties pressing for relief on living costs.
- Constitutional shortcut. Article 49.3 lets the government adopt a text without a vote, at the risk of a no-confidence motion. Budget ordinances are a further fallback if parliament fails to act by year-end.
- Failure. A rejected budget or a fallen government would leave 2027 spending on temporary footing and push the deficit above target.
The riots complicate each route. Concessions to protesters would soften the consolidation, while a hard line risks more unrest and a harder parliamentary fight. Either outcome affects how much of a risk premium bond investors build into the OAT.
How Do Interest Rates Fit Into the Picture?
French sovereign stress is largely a domestic fiscal story, but it sits within the ECB policy rate framework. The European Central Bank sets short-term interest rates for the euro area and cannot target France alone. Its crisis tools exist for disorderly market conditions, not for fiscal slippage, and a spread near 142 basis points is elevated but not disorderly.
That leaves the pressure on Paris. The government has said it expects to deliver a budget by year-end, which it argues will contain slippage and keep spreads in a range of about 120 to 150 basis points. A move above the October 2 peak would test that assumption and could draw attention to the rating outlook for French sovereign debt.
Geopolitical and Economic Dimension
France is the euro area's second-largest economy, and its political stability underpins the currency bloc's fiscal credibility. A prolonged standoff would tie up Macron's government at a time when Europe is negotiating defense spending and industrial policy. It would also give investors a reason to demand a wider premium across the euro area periphery.
The domestic economy faces a squeeze from two sides. Government forecasts for 2027 growth of about 1% leave little cushion, while fiscal tightening and higher funding costs weigh on demand. Retailers and local businesses in areas hit by looting also face repair costs and lost trading days.
Outlook
The next several days set the tone. Parliamentary votes on the 2027 budget and the pace of unrest will decide whether the 10-year yield settles near 4.86% or tests the 5% level last seen in 2002. A credible path to a 5.0% deficit would narrow the spread toward the lower end of the government's range. A failed vote or fresh violence would widen it past the October 2 peak. Until then, French assets will trade on political headlines as much as on economic data.
Mentioned tickers: none