Pomegra
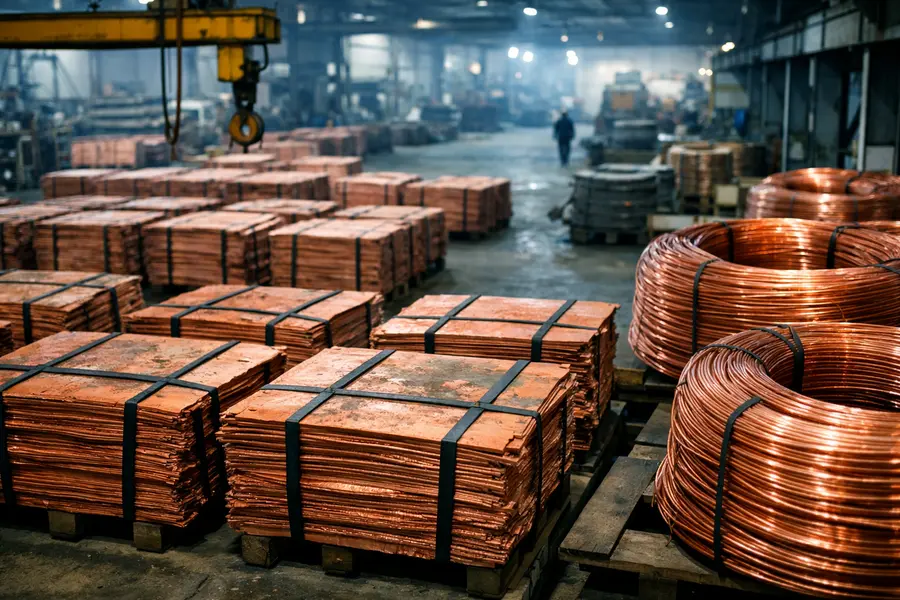
Copper surged past $5.45 per pound to an all-time high as US tariff arbitrage emptied London Metal Exchange warehouses and China halted copper exports following acute sulfuric-acid shortages at domestic smelters.
- Copper broke $5.45/lb on the LME, a record, as global warehouse stockpiles fell to multi-decade lows driven by US-bound arbitrage flows.
- China formally suspended copper cathode exports after sulfuric-acid byproduct gluts forced curtailments at major smelting complexes, tightening global refined supply.
- Mining equities FCX, SCCO, and COPX rallied sharply; broader commodity desks flagged the supply shock as potentially structural rather than cyclical.
Lead
Copper broke through $5.45 per pound on the London Metal Exchange on Tuesday, registering a record high as two simultaneous supply shocks converged: a multi-month arbitrage trade routed physical metal toward the United States ahead of and following import tariff implementation, draining LME-registered warehouse inventories worldwide to their lowest levels in more than two decades, while Beijing suspended exports of refined copper cathode after a cascade of smelter curtailments tied to an acute domestic surplus of sulfuric acid.
What Triggered the LME Stockpile Collapse?
The root cause was a persistent and widening price premium on the CME copper contract over the LME benchmark, a gap that opened when Washington announced elevated import tariffs on copper earlier this year. Traders and physical merchants responded by rerouting refined copper - primarily copper cathode previously destined for Asian and European consumers - toward US-registered warehouses and delivery points, capturing the arbitrage spread. Over subsequent months, LME global warehouse tonnage declined by roughly 70 percent from its 2024 peaks, with European and Asian hub inventories recording the steepest drawdowns. As on-warrant LME stocks fell below critical thresholds, the backwardation structure of the futures curve intensified, signaling immediate physical tightness and drawing speculative length into the front month.
Why Did China Suspend Copper Exports?
China's export halt stemmed from an industrial supply-chain problem inside its domestic smelting sector. Copper smelting generates sulfuric acid as an unavoidable byproduct; Chinese refiners expanded cathode capacity aggressively through 2023 and early 2024, flooding the domestic sulfuric-acid market. Prices for sulfuric acid in China collapsed, eroding smelter economics to the point that several large complexes - particularly in Jiangxi and Shandong provinces - curtailed or idled refining operations entirely. With Chinese refined copper output declining, the government moved to retain available cathode supply for domestic industrial consumption, formally restricting exports. China represents roughly half of global refined copper output; any material disruption to its export flows removes a critical balancing mechanism for the rest of the world's copper consumers.
Market Reaction
Freeport-McMoRan (FCX) shares rose more than 6 percent in New York trading, reaching their highest level since 2022, as investors priced in substantially higher realized copper prices for the company's American and international mining operations. Southern Copper (SCCO) added nearly 5 percent. The Global X Copper Miners ETF (COPX) surged more than 7 percent on elevated volume, with the session ranking among its highest-turnover days on record. Broader industrial metals indices climbed in sympathy, with aluminum and zinc also posting gains as traders reassessed the supply discipline of the metals complex globally. SPDR Gold Shares (GLD) and iShares Silver Trust (SLV) edged higher as the commodity rally attracted broad macro flows. Equity benchmarks in copper-producing economies - Chile, Peru, and Australia - outperformed developed-market peers.How Does Tariff Arbitrage Reshape Global Copper Flows?
The mechanism is straightforward but its scale was underestimated. When a durable price differential emerges between two futures markets referencing the same physical commodity, arbitrageurs borrow metal from wherever it is cheapest and deliver it where the premium is highest. In this episode, LME-warehoused metal became the funding inventory for US-bound shipments. The process does not destroy copper; it relocates it. But the velocity of the relocation - compressing what might have been a gradual multi-year rebalancing into a period of months - overwhelmed the logistical capacity of the shipping and warehousing infrastructure and left non-US consumers competing for a shrunken pool of immediately available metal. Spot premiums in Europe and Southeast Asia climbed sharply as downstream fabricators, particularly wire-rod mills and tube producers, entered the spot market simultaneously.
Strategic Context
The confluence of tariff-driven arbitrage and China's smelter curtailment cycle arrives against a longer-term backdrop of structural underinvestment in new copper mine supply. No major greenfield copper mine has moved from discovery to production in under a decade. Existing operations in Chile, the world's largest producing nation, have faced persistent grade decline, water constraints, and rising input costs. Peru, the second-largest producer, has contended with recurring community and political disruptions. The result is a supply pipeline that most industry analysts regard as insufficient to meet demand from grid infrastructure buildout, electric-vehicle manufacturing, and data-center power systems through 2030. The current price spike, while partly driven by financial and policy mechanics, is accelerating a conversation across mining boards and national resource ministries about permitting timelines and project financing.
Outlook
Copper's breach of $5.45 per pound reflects a rare convergence of policy-driven demand pull from the United States, a structural supply shock from China's smelting sector, and an already depleted LME inventory buffer. Near-term resolution depends on whether the CME-LME arbitrage window narrows enough to halt further metal migration and whether Chinese smelters resume operations as sulfuric-acid markets rebalance. Both processes are measured in months, not weeks. If neither resolves quickly, front-month LME copper has limited technical resistance before $6.00 per pound. Mining equities with unhedged copper exposure remain the primary listed instrument for investors seeking direct alignment with the physical market move.