Pomegra
China's economy grew 4.5% in the third quarter of 2026, beating forecasts as AI-linked chip exports offset weak consumer demand and a deepening property slump.
- China's third-quarter GDP rose 4.5% year over year, ahead of the 4.4% forecast and up from 4.3% in the second quarter.
- September retail sales rose just 1.1%, while fixed asset investment fell 7.2% in the first nine months.
- The yuan rose to a four-year high, and the data reduces pressure on Beijing for immediate easing.
Lead
China's gross domestic product expanded 4.5% from a year earlier in the July-September quarter, according to the National Bureau of Statistics. That topped the 4.4% expected by economists and improved on the 4.3% recorded in the second quarter, which had been a three-year low. The outcome was driven by exports tied to the global artificial intelligence build-out. Household spending and investment stayed weak.
Growth over the first nine months of 2026 stands at 4.6%, inside the government's full-year target range of 4.5% to 5.0%.
What Happened in China's Third Quarter?
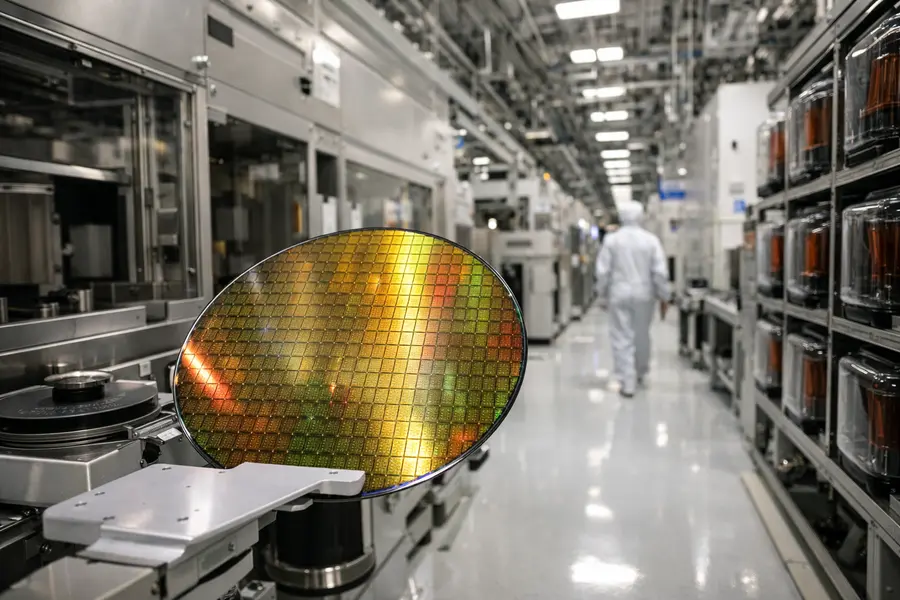
China's third-quarter GDP grew 4.5%, a two-tenths acceleration from the prior quarter. Export strength was the main source of the pickup. Shipments of semiconductors and electronic components surged as data-centre demand for AI hardware lifted orders across Asian supply chains.
Industrial output rose 5.5% in September from a year earlier. That beat the 5.4% forecast and followed 5.2% growth in August. High-tech manufacturing, chip production and new-energy vehicles led the gains.
Retail sales, the main gauge of consumer demand, rose 1.1% in September. The figure beat the 0.5% forecast and improved on 0.4% in August, but it remains far below the pace needed to make household spending a growth engine.
Why Is Domestic Demand Still So Weak?
Domestic demand is weak because households remain cautious and the property sector is still contracting. Fixed asset investment in urban areas fell 7.2% in the first nine months of the year. Real estate development investment dropped 20.6% over the same period.
The property downturn has weighed on household wealth for several years, since housing accounts for the bulk of Chinese family savings. Falling home values have encouraged saving over spending. Local governments, which depend on land sales for revenue, have also had less room to fund infrastructure.
The result is an economy running on two tracks. Export-oriented manufacturing, especially technology hardware, is expanding at a healthy pace. Consumption, construction and private investment are not.
How Did Markets React?
Markets treated the data as a mild positive. The yuan climbed to a four-year high after the release, and the Australian dollar, a common proxy for China-sensitive trade, gained about 0.4% against the US dollar.
The stronger headline number also changes the policy calculus. The People's Bank of China has held its benchmark policy rate steady since a cut in May 2025. A GDP beat, combined with a retail sales upside surprise, lowers the urgency for broad-based easing. Investors tracking global interest rates now see less chance of an imminent move from Beijing, though targeted support for consumption and property remains on the table.
A firmer yuan carries its own trade-off. It improves purchasing power for imports and eases pressure on dollar-denominated debt, but it raises costs for exporters whose growth is carrying the economy.
What Does the AI Export Boom Mean for China's Growth Model?
The AI export boom means China's growth is leaning more heavily on external demand tied to a single technology cycle. Strong chip and electronics shipments reflect spending by global cloud providers and AI developers, which sets the pace for Asian manufacturers regardless of conditions in China's own consumer economy.
That linkage creates two sensitivities. The first is the capital-expenditure cycle abroad: a slowdown in data-centre investment would feed quickly into Chinese and regional export orders. The second is trade policy. Export controls and tariffs on advanced technology remain a standing risk to the high-tech segment that is now driving industrial output.
For policymakers, the composition of growth matters as much as the headline. An economy that reaches its target through exports faces criticism from trading partners and remains exposed to external shocks. Rebalancing toward consumption has been a stated goal for years, and the 1.1% retail sales figure shows how far it still has to go.
What Comes Next for the Chinese Economy?
The fourth quarter will test whether the export-led recovery can hold. Reaching the lower end of the 4.5% to 5.0% target looks achievable given the 4.6% nine-month pace, so the immediate pressure to stimulate is lower than it was in the spring.
The main near-term variables are:
- Consumer spending: whether recent improvement in retail sales proves durable or reflects base effects.
- Property: whether the 20.6% contraction in real estate investment stabilizes.
- Exports: whether global AI hardware orders stay elevated into year-end.
- Policy: whether the PBOC and fiscal authorities move toward targeted consumption support.
Outlook
China's third-quarter GDP growth of 4.5% beat forecasts and kept the economy within its annual target, but the quality of growth remains uneven. AI-linked exports and high-tech manufacturing are carrying output, while retail sales, investment and property remain weak. With the yuan at a four-year high and the central bank holding rates, the policy focus now shifts to whether domestic demand can recover enough to reduce dependence on the global technology cycle.
Mentioned tickers: N/A