Pomegra
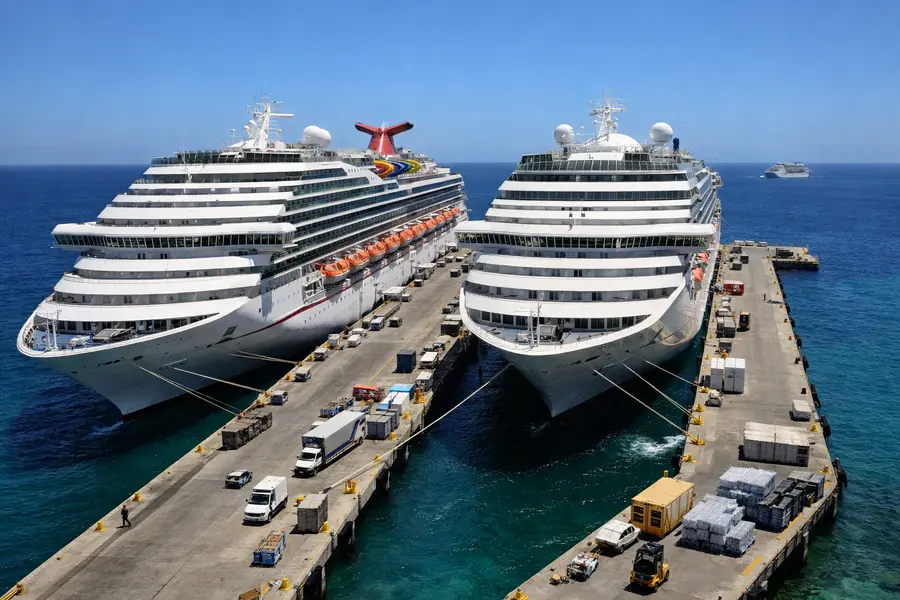
Carnival Corporation and Norwegian Cruise Line Holdings fell simultaneously to fresh 52-week lows as a 5.43% 30-year Treasury yield and $105 Brent crude deliver a compounding cost squeeze on leveraged cruise operators.
- CCL dropped to $1.88 and NCLH fell to $3.96, both registering 52-week lows in Thursday's session amid heavy sector selling.
- The 5.43% 30-year Treasury yield is escalating refinancing costs on pandemic-era debt loads that neither operator has fully retired.
- Brent crude at $105 per barrel is compressing fuel margins while inflation fatigue erodes consumer willingness to commit discretionary travel budgets.
Lead
Shares of Carnival Corporation (CCL) and Norwegian Cruise Line Holdings (NCLH) collapsed to simultaneous 52-week lows Thursday, with CCL touching $1.88 and NCLH reaching $3.96 as two converging macro forces -- a 5.43% 30-year Treasury yield and Brent crude above $105 per barrel -- tightened a financial vise around an industry still carrying the debt architecture assembled during the COVID-19 shutdown years. The dual deterioration in both cost lines triggered broad-based institutional selling across the consumer discretionary travel sector, with no near-term relief visible on either front.
Why Did Cruise Stocks Break to New Lows Now?
The break lower reflects the moment when two previously manageable pressures became simultaneously acute. Carnival and Norwegian each refinanced heavily between 2020 and 2022, issuing long-duration notes and secured bonds to survive fleet idling. With the 30-year Treasury yield now at 5.43% -- its highest level in over a decade -- those instruments face materially higher rollover costs as maturities approach. At the same time, Brent crude crossing $105 per barrel directly compresses cruise operating margins: fuel represents between 12% and 15% of total operating expenses for large-scale operators, and neither company carries sufficient hedging coverage to neutralize a sustained move at these levels. The combination moved from a sector-level concern to a stock-specific catalyst as investors priced in earnings revisions.
How Does the 5.43% Treasury Yield Affect Cruise Debt?
Interest rates at current levels convert what were manageable refinancing timelines into urgent balance sheet decisions. Carnival carries a debt load exceeding $28 billion, the residue of survival financing issued at far lower yields. Norwegian's leverage profile is proportionally comparable relative to its smaller fleet. Rolling even a fraction of that debt at spreads benchmarked against a 5.43% long end adds hundreds of millions in annual interest expense -- directly reducing free cash flow available for fleet investment, share buybacks, or dividend restoration. Credit markets are already pricing that risk: spreads on both issuers' existing bonds have widened materially, signaling that institutional fixed-income desks view the refinancing calendar as a live concern rather than a manageable long-term horizon.What Does $105 Brent Crude Mean for Ticket Pricing and Margins?
Elevated energy prices create a structural dilemma for cruise operators: absorb the cost shock through lower margins or pass it to consumers through surcharges and ticket price increases at precisely the moment when inflation fatigue is weakening bookings. North American leisure travelers, who represent the dominant revenue base for both CCL and NCLH, have spent three consecutive years absorbing higher prices across housing, food, and services. Discretionary travel, particularly high-ticket multi-night cruise packages, is among the first categories to see reservation deferrals when household budgets tighten. Pricing power -- which both operators cited as a post-pandemic recovery tailwind through 2024 -- is now a liability if management attempts to pass through fuel cost increases. Holding prices flat while fuel runs at $105 per barrel simply accelerates margin compression.
Market Reaction
The move in CCL and NCLH reflected sector-wide repositioning rather than isolated stock-specific events. Royal Caribbean Group (RCL) also traded lower in sympathy, though it held above its own 52-week low, reflecting a modestly stronger balance sheet and a fuel hedging program viewed by the market as more comprehensive. The S&P 500 consumer discretionary sub-index declined on the session as the cruise sector dragged leisure and travel names broadly lower. Options activity in both CCL and NCLH spiked, with elevated put volume suggesting institutional traders are positioning for further downside rather than treating current levels as a buying opportunity.
What Comes Next for Cruise Operators Under This Macro Pressure?
Near-term catalysts will center on whether the Federal Reserve's next policy signals alter the long-end yield trajectory and whether Brent crude stabilizes below $100 per barrel -- the level at which both operators' fuel budgets were modeled in their most recent forward guidance. Absent relief on either dimension, both CCL and NCLH face the prospect of downward earnings revisions heading into fourth-quarter reporting. Analysts watching the sector are focused on two metrics: net yield per passenger cruise day, which will reveal whether ticket pricing is holding, and debt-service coverage ratios, which will quantify the refinancing pressure. Any quarterly update that shows deterioration in both simultaneously could extend the selloff beyond current 52-week lows. Management teams at both companies are under increasing pressure to address the debt maturity schedule in public communications before year-end.
Outlook
Carnival Corporation and Norwegian Cruise Line Holdings face a structurally difficult environment as long as 30-year Treasury yields remain above 5% and Brent crude holds above $100 per barrel. The double squeeze -- rising refinancing costs against a backdrop of inflation-fatigued consumers -- leaves both operators with limited options and narrowing financial flexibility. Until one or both macro pressures ease materially, the sector offers institutional investors little fundamental reason to rebuild positions.