The Long Strangle: A More Affordable Volatility Bet
🌟 The Smart Trader's Alternative to the Straddle
In our last discussion, we explored the long straddle, a powerful tool for betting on pure volatility. But what if the cost of entry—the combined premium of two at-the-money options—is just too steep? High premiums create wide break-even points, demanding a massive move to turn a profit. This is where the long strangle comes in.
The long strangle is the straddle's more affordable cousin. It's a strategy designed for the same purpose—to profit from a significant price swing in either direction—but with a lower upfront cost. This makes it more accessible and, in many cases, a more capital-efficient way to trade volatility. This article will dissect the long strangle, revealing its mechanics, its key advantages and disadvantages, and how it differs from the straddle.
The Anatomy of a Long Strangle
The structure of a long strangle is similar to a straddle, with one key difference: the strike prices are out-of-the-money.
A long strangle consists of two simultaneous transactions:
- Buy one Out-of-the-Money (OTM) Call Option.
- Buy one Out-of-the-Money (OTM) Put Option.
Both options must have the same underlying asset and the same expiration date, but they have different strike prices. The call's strike price is above the current stock price, and the put's strike price is below it.
This use of OTM options is what makes the strangle cheaper than the straddle. The trade-off is that the stock must move even further to become profitable.
The net debit paid for the two options represents your maximum possible loss, making this a defined-risk strategy.
The P&L Profile: Wider Break-Evens for a Lower Cost
The P&L diagram for a long strangle has a wider, flatter bottom compared to the V-shape of a straddle. This flat area represents the range between the two strike prices where the maximum loss is realized.
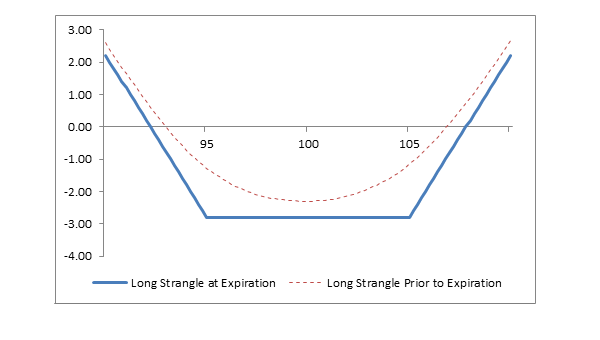
To calculate the break-even points, you use the same logic as the straddle:
- Upper Break-Even Point: Call Strike Price + Net Debit Paid
- Lower Break-Even Point: Put Strike Price - Net Debit Paid
Example:
- Stock: ACME Corp. trading at $100.
- Action: Buy a $105 strike call for $1.50 and a $95 strike put for $1.30.
- Net Debit (Max Loss): $1.50 + $1.30 = $2.80 per share ($280 per contract set).
- Upper Break-Even: $105 + $2.80 = $107.80.
- Lower Break-Even: $95 - $2.80 = $92.20.
For this trade to be profitable at expiration, ACME must rally above $107.80 or fall below $92.20. If the stock price finishes between $95 and $105, both options expire worthless, and the maximum loss of $280 is incurred.
Straddle vs. Strangle: A Deeper Dive into the Trade-Offs
Choosing between a straddle and a strangle is one of the most common decisions a volatility trader faces. While both strategies aim to profit from a large price move, their different structures lead to significant trade-offs in cost, risk, and probability.
The Cost-Probability Spectrum:
Think of these two strategies on a spectrum. At one end, the long straddle is the premium, all-in bet. By buying at-the-money (ATM) options, you pay a higher price, but you give yourself the highest probability of success. The stock doesn't need to move as far for the position to become profitable. This is like buying a more expensive ticket for a seat closer to the stage—you pay more, but you have a better view.
At the other end, the long strangle is the budget-friendly alternative. By buying out-of-the-money (OTM) options, you significantly reduce your upfront cost (your maximum risk). However, this comes at the cost of probability. The stock must make a much larger move to reach your now-wider break-even points. This is like buying a cheaper ticket in the nosebleed section—you saved money, but you need the show to be truly spectacular to feel like you got your money's worth.
| Feature | Long Straddle | Long Strangle |
|---|---|---|
| Cost | Higher (ATM options are more expensive) | Lower (OTM options are cheaper) |
| Break-Evens | Closer together | Farther apart |
| Required Move | Smaller move needed to profit | Larger move needed to profit |
| Max Loss | Higher (equal to the higher premium) | Lower (equal to the lower premium) |
| Theta Decay | Higher absolute dollar decay | Lower absolute dollar decay |
| Best For | Higher conviction in a move, but less certainty on magnitude. | Higher conviction in the magnitude of the move. |
Your choice ultimately depends on your forecast for volatility and the specific characteristics of the underlying stock. A careful analysis of the options chain and the implied move is critical.
Choosing Your Strikes: The Art of the Strangle
Unlike a straddle, where the strike price is simply at-the-money, a strangle requires you to make a decision: how far out-of-the-money should the strikes be? This is not a random choice; it's a strategic one that defines the character of your trade.
-
Narrow Strangle (Strikes closer to the stock price):
- Cost: More expensive.
- Break-Evens: Closer together.
- Probability: Higher chance of being profitable.
- Best for: When you expect a solid, but not necessarily explosive, move. This is a middle ground between a straddle and a wide strangle.
-
Wide Strangle (Strikes further from the stock price):
- Cost: Cheaper.
- Break-Evens: Much farther apart.
- Probability: Lower chance of being profitable.
- Best for: When you are betting on a truly massive, outlier event. This is a lower-cost, lower-probability, but higher-potential-reward trade.
A common approach is to select strikes that correspond to a certain delta, for example, buying the 30-delta call and the 30-delta put. The delta can be used as a rough proxy for the probability of an option expiring in-the-money. A 30-delta option has an approximate 30% chance of finishing in-the-money. This provides a more systematic way to select your strikes than simply guessing.
The Double-Edged Sword: Vega and Theta
Like the straddle, the long strangle is a game of balancing volatility (Vega) and time decay (Theta).
- Positive Vega: A long strangle is a long vega position. This means it profits from an increase in implied volatility. If the market's expectation of future price swings (IV) increases after you've placed your trade, the value of both your call and your put will rise, even if the stock price hasn't moved yet. This is why strangles are most effective when you believe that current IV is under-pricing the potential for a future move.
- Negative Theta: Time decay is the primary enemy of the long strangle. Since you are the owner of two options, your position loses value every single day due to the passage of time. This is known as negative theta. The position is in a constant race against the clock: the stock must make its move before theta decay eats away the entire premium you paid. The rate of time decay accelerates as expiration approaches, making longer-dated strangles less susceptible to theta's immediate impact.
A successful strangle trader needs the stock to move significantly, and to do so quickly, to outpace the relentless drain of theta.
When is the Long Strangle the Right Tool?
The long strangle shines in the same scenarios as the long straddle, but it's particularly well-suited for traders who want to reduce their upfront cost and are confident that the impending move will be exceptionally large.
- High-Conviction Event Trades: If you strongly believe an earnings report or an FDA decision will cause a massive gap in the stock price, the strangle's lower cost and wider profit zone can be an advantage.
- Trading High-Priced Stocks: For expensive stocks, the cost of an ATM straddle can be prohibitive. A strangle offers a more affordable way to get exposure to their volatility.
- When IV is High but Expected to Go Higher: If implied volatility is already elevated, a straddle can be very expensive. A strangle allows you to enter a long-volatility position at a lower cost basis, though you still face the risk of IV crush.
💡 Conclusion: The Strategic Choice for Volatility Plays
The long strangle is far more than just a "cheap straddle." It's a strategic tool that allows you to fine-tune your bet on volatility. By giving you control over the strike prices, it lets you define the precise risk, cost, and probability profile of your trade. It's the embodiment of the options principle of trade-offs: you give up a higher probability of success for a lower cost of entry and a lower maximum loss.
This strategy is for the trader who has a strong conviction that a large move is coming and wants to structure a trade that maximizes leverage to that event while minimizing capital at risk.
Here’s what to remember:
- It's a Trade-Off: You are trading a lower cost and lower max loss for wider break-even points and a lower probability of profit compared to a straddle.
- Strike Selection is Key: The distance of your strikes from the current stock price determines the entire risk/reward profile of your trade. Don't choose them arbitrarily.
- Volatility is Your Friend, Time is Your Foe: You need a significant price move and/or a spike in implied volatility to overcome the constant headwind of time decay.
Challenge Yourself: Find a stock with high implied volatility (e.g., one with an upcoming earnings report or in a volatile sector). Go to its options chain and price out three different long strangles with the same expiration date:
- A narrow strangle (e.g., 40-delta call and put).
- A standard strangle (e.g., 30-delta call and put).
- A wide strangle (e.g., 20-delta call and put).
Compare the cost, maximum loss, and break-even points for each. Notice how dramatically the risk/reward profile changes based on your strike selection. Which one would you choose and why?
➡️ What's Next?
We've now covered two powerful strategies for buying volatility. But what about selling it? In the next article, "The Short Straddle and Strangle: Profiting from Market Calm", we'll flip the script and explore how to profit when you expect the market to stay quiet.
Mastering both sides of the volatility coin is what separates the novice from the pro. Keep pushing forward.
📚 Glossary & Further Reading
Glossary:
- Long Strangle: An options strategy involving the purchase of an out-of-the-money call and an out-of-the-money put with the same expiration but different strike prices.
- Out-of-the-Money (OTM): An option that has no intrinsic value. A call is OTM if its strike price is above the current stock price; a put is OTM if its strike price is below the current stock price.
Further Reading: