The Long Call and Put Butterflies: Pinpointing a Price Target
🌟 From Neutral to Directional: The Versatile Butterfly
In our previous discussions on the iron condor and iron butterfly, we focused on market-neutral strategies. These trades profit when a stock stays within a range, regardless of direction. But what if you have a directional view? What if you believe a stock will not only move, but will land at a specific price target by a certain date?
This is where the long call and put butterfly spreads come in. These strategies take the same defined-risk structure of the iron butterfly but are constructed using either all calls or all puts. The result is a low-cost, high-reward strategy for pinpointing a precise price target. This article will teach you how to construct both call and put butterflies and how to use them to make targeted, directional bets.
The Anatomy of a Long Call Butterfly
A long call butterfly is a three-legged strategy that combines a bull call spread and a bear call spread.
It is constructed as follows:
- Buy one In-the-Money (ITM) Call Option.
- Sell two At-the-Money (ATM) Call Options.
- Buy one Out-of-the-Money (OTM) Call Option.
All three options must have the same expiration date, and the strike prices must be equidistant. The position is established for a net debit, which represents your maximum possible loss.
The goal is for the stock to be exactly at the middle strike price at expiration.
The P&L Profile: A Familiar Tent Shape
The P&L diagram of a long call butterfly is identical to that of an iron butterfly—a sharp, tent-like shape.
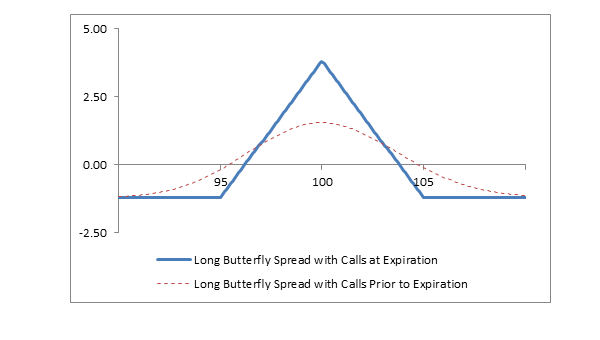
- Maximum Profit: The difference between the strike prices, minus the net debit paid. This is achieved if the stock is at the middle strike at expiration.
- Maximum Loss: The net debit paid for the spread. This occurs if the stock is below the lowest strike or above the highest strike at expiration.
- Break-Even Points:
- Upper: Highest Strike - Net Debit
- Lower: Lowest Strike + Net Debit
The Long Put Butterfly: The Other Side of the Coin
The long put butterfly is the exact same strategy, but constructed with puts instead of calls:
- Buy one ITM Put Option.
- Sell two ATM Put Options.
- Buy one OTM Put Option.
The P&L profile, maximum profit, maximum loss, and break-even points are all identical to the long call butterfly. So why choose one over the other?
The choice between a call or put butterfly can come down to subtle factors like:
- Cost: Sometimes, due to volatility skew, one version might be slightly cheaper to establish than the other.
- Early Assignment Risk: If the stock pays a dividend, an in-the-money call is more likely to be assigned early than a put.
- Directional Bias: Some traders prefer to use call butterflies for bullish targets and put butterflies for bearish targets, even though the P&L is the same.
The Debit vs. Credit Distinction
It's important to distinguish between a long butterfly (made with all calls or all puts) and an iron butterfly (made with both calls and puts).
| Feature | Long Butterfly (Call or Put) | Iron Butterfly |
|---|---|---|
| Entry | Net Debit | Net Credit |
| Max Profit | Spread Width - Debit | Net Credit |
| Max Loss | Net Debit | Spread Width - Credit |
| Margin | Cost of the debit | Margin required for the credit spread |
While the P&L diagrams are the same, the mechanics of how you enter and exit the trades, and how they are margined, are different.
Managing the Long Butterfly
Like all options strategies, the long butterfly requires active management.
- Profit Taking: The maximum profit on a butterfly is only achieved at expiration if the stock price is exactly at the middle strike. This is a rare occurrence. A more practical approach is to take profits when the trade has reached a certain percentage of its maximum potential, such as 50%.
- Adjustments: If the stock price moves away from your target, you can adjust the butterfly. One common adjustment is to roll the entire position up or down to re-center it around the new stock price. This will typically cost a small debit, which will increase your maximum risk.
- Exiting for a Loss: If the stock price moves outside of your break-even points, it's often best to close the trade for a small loss rather than holding it to expiration and risking the maximum loss.
When to Use a Long Butterfly
The long butterfly is a strategy for making a very specific forecast. It's not a strategy to be used lightly, but in the right circumstances, it can be very effective.
- Targeting a Price Pin: If you have a strong reason to believe a stock will finish at a specific price on a specific date, the butterfly offers an excellent risk/reward profile. This could be due to technical analysis, such as a stock trading in a very tight range, or fundamental analysis, such as an expected announcement.
- Low-Cost Directional Bet: If you are bullish but don't want to risk a lot of capital, you can place the center strike of a call butterfly above the current stock price. This creates a cheap, defined-risk bet on the stock rising to your target. This is often referred to as a "broken-wing" butterfly.
- Betting Against a Move: If you believe a stock has moved too far, too fast, you can center a butterfly at a price you expect it to revert to. This is a contrarian strategy that can be very profitable if you are correct.
- Earnings Plays: Some traders will use a butterfly spread around an earnings announcement. If they believe the expected move is overpriced, they can sell an iron butterfly. If they believe the stock will move to a specific price, they can use a long butterfly.
💡 Conclusion: The Sniper Rifle of Options Strategies
The long call and put butterfly spreads are the sniper rifles of the options world. They are not for every situation, but when you have a precise target in mind, they are incredibly effective. They allow you to make a low-cost, defined-risk bet on a specific outcome, offering a massive potential reward if your forecast is correct. They are a testament to the flexibility of options, allowing you to craft a position that perfectly matches a very specific market thesis.
Here’s what to remember:
- It's a Bet on a Specific Price: The butterfly is not a range-bound strategy like the condor; it's a target-based strategy. Your profitability depends on the stock's price being very close to the middle strike at expiration.
- Low Cost, High Reward: The primary appeal of the butterfly is the ability to risk a small amount of capital for a large potential profit. The risk/reward ratio of a butterfly can be very attractive, often 5-to-1 or even 10-to-1.
- Theta Can Be Tricky: Unlike the iron butterfly, the theta profile of a long butterfly can change depending on where the stock is relative to your strikes. It's not always a pure time decay play. When the stock is at the middle strike, theta is positive. When the stock moves outside the wings, theta becomes negative.
- Calls vs. Puts: The choice between a call and put butterfly is often a matter of preference and cost. Due to volatility skew, one may be slightly cheaper than the other.
Challenge Yourself: Pick a stock and a price target you believe it will reach in the next 30-45 days. Go to the options chain and construct a long call butterfly centered at your target price. Note the debit, the max profit, and the max loss. Now, construct a long put butterfly with the same strikes. Is there a difference in the cost? If so, why do you think that is? How does the risk/reward ratio of this trade compare to simply buying a call option?
➡️ What's Next?
We've now covered a wide array of strategies for trading volatility, from the wide-winged condors to the precision of the butterfly. But how do you know which one to choose? In our next article, "When to Use Which Volatility Strategy: A Decision Framework", we'll tie everything together and provide a practical guide for selecting the right tool for the job.
📚 Glossary & Further Reading
Glossary:
- Long Call Butterfly: A three-legged options strategy consisting of one long ITM call, two short ATM calls, and one long OTM call.
- Long Put Butterfly: A three-legged options strategy consisting of one long ITM put, two short ATM puts, and one long OTM put.
- Net Debit: The total cost of an options position when the premiums paid exceed the premiums received.
Further Reading: